This is the Daily Shot Brief, an abridged version of The Daily Shot. If you would like to subscribe to the full-length Daily Shot (see example), please register here.
United States
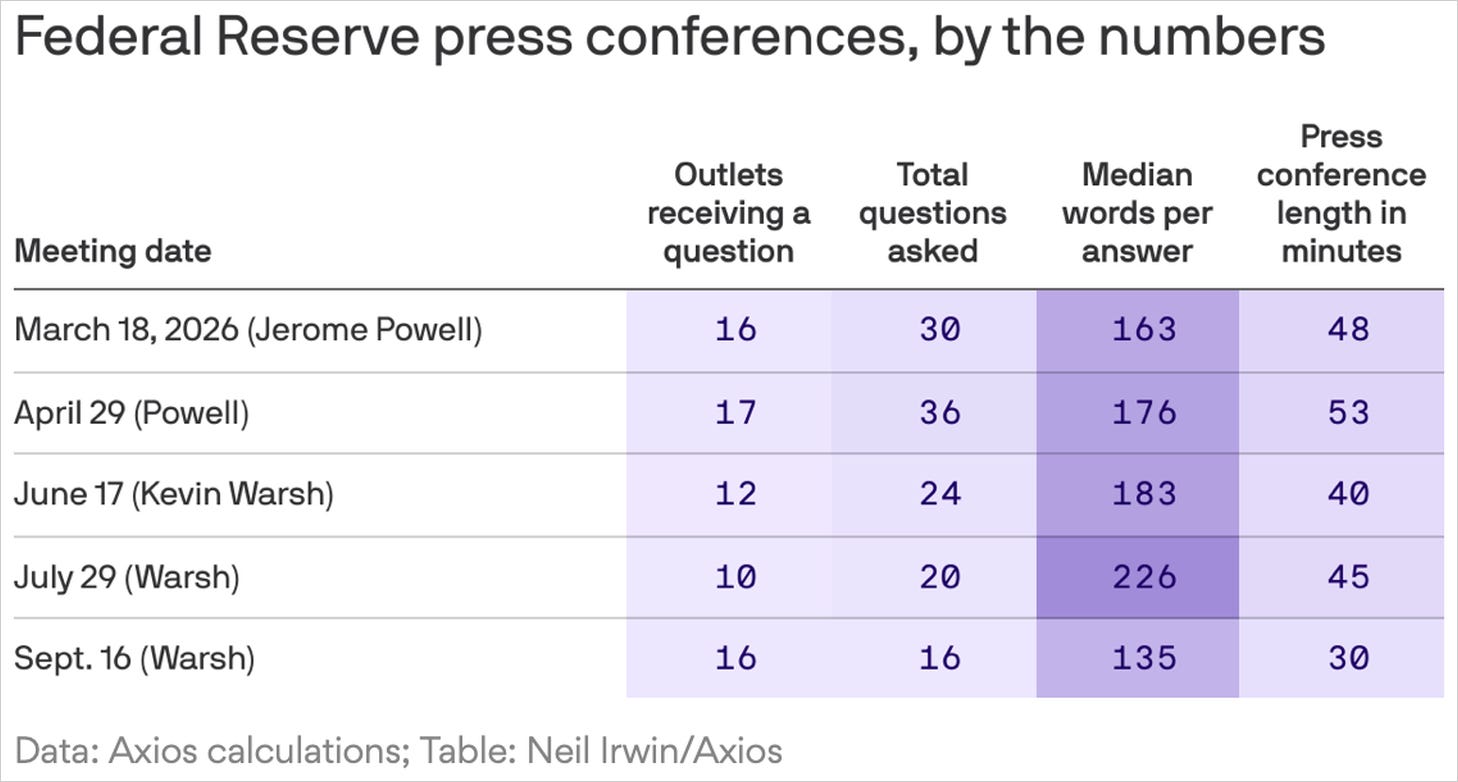
In the latest press conference, Fed Chair Kevin Warsh eliminated follow-up questions, shortened his responses, broadened the range of outlets called on, and cut the total briefing duration to about 30 minutes.
United Kingdom
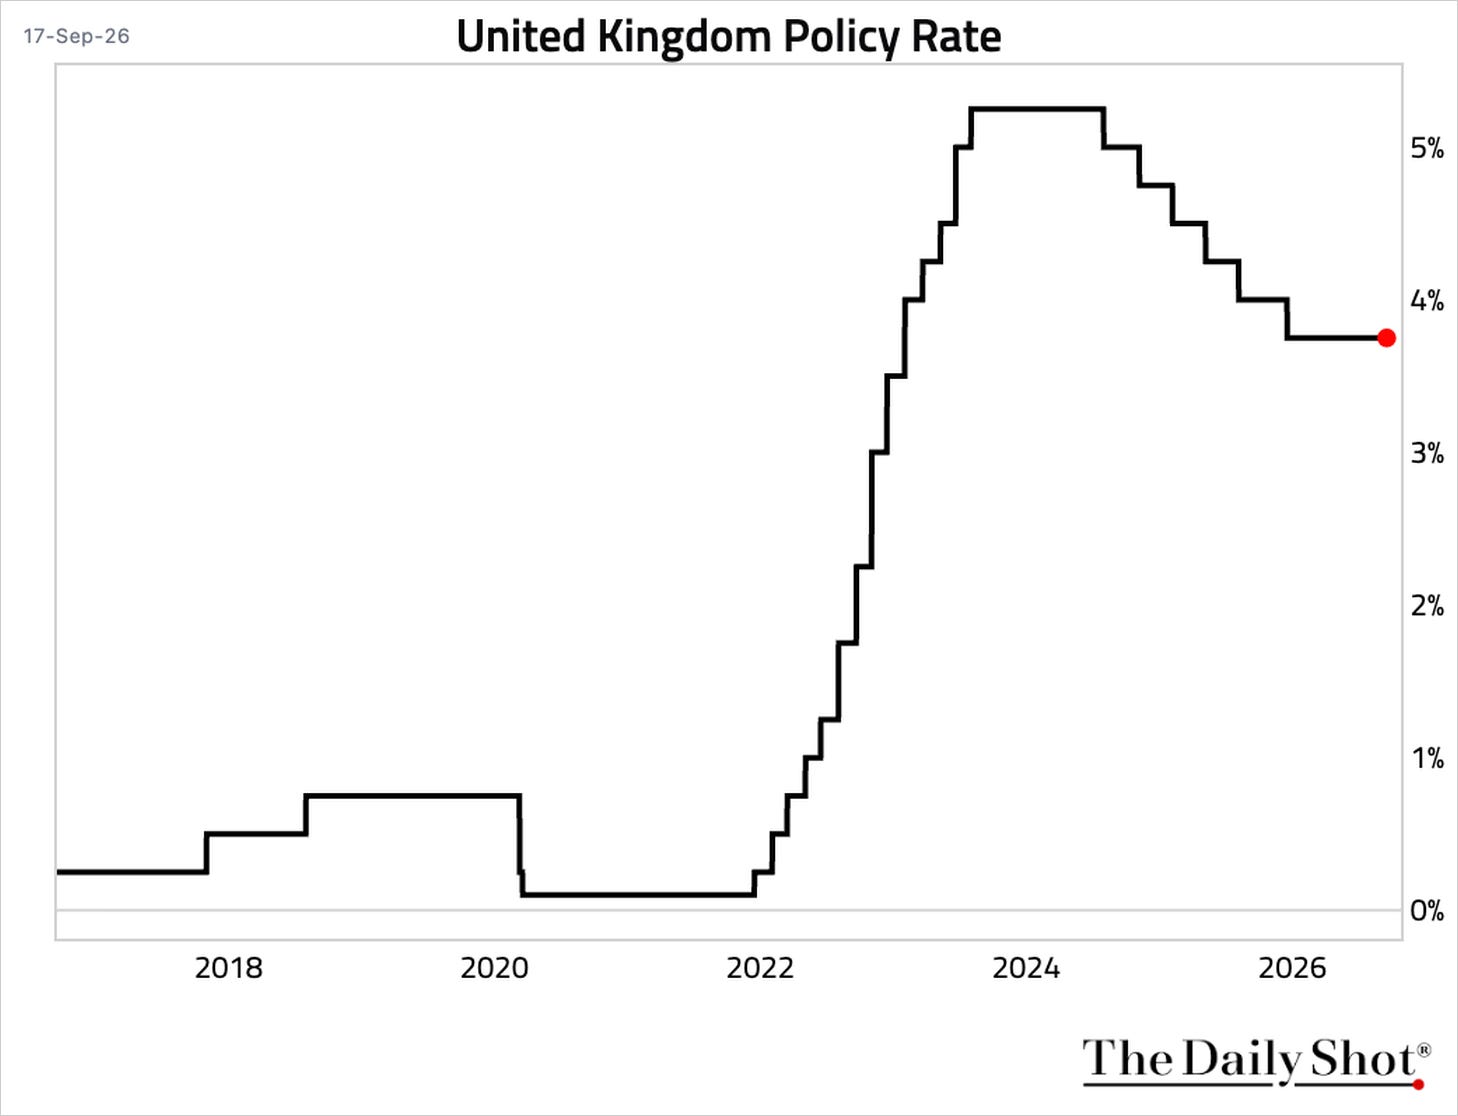
The Bank of England held its Bank Rate steady at 3.75% in a six-to-three split, with members Pill, Greene, and Mann dissenting in favor of a 25 bps rate hike. The Monetary Policy Committee reiterated that there is little evidence so far of material second-round effects from higher energy prices, although it indicated that upside risks to the inflation outlook have increased.
Euro Area
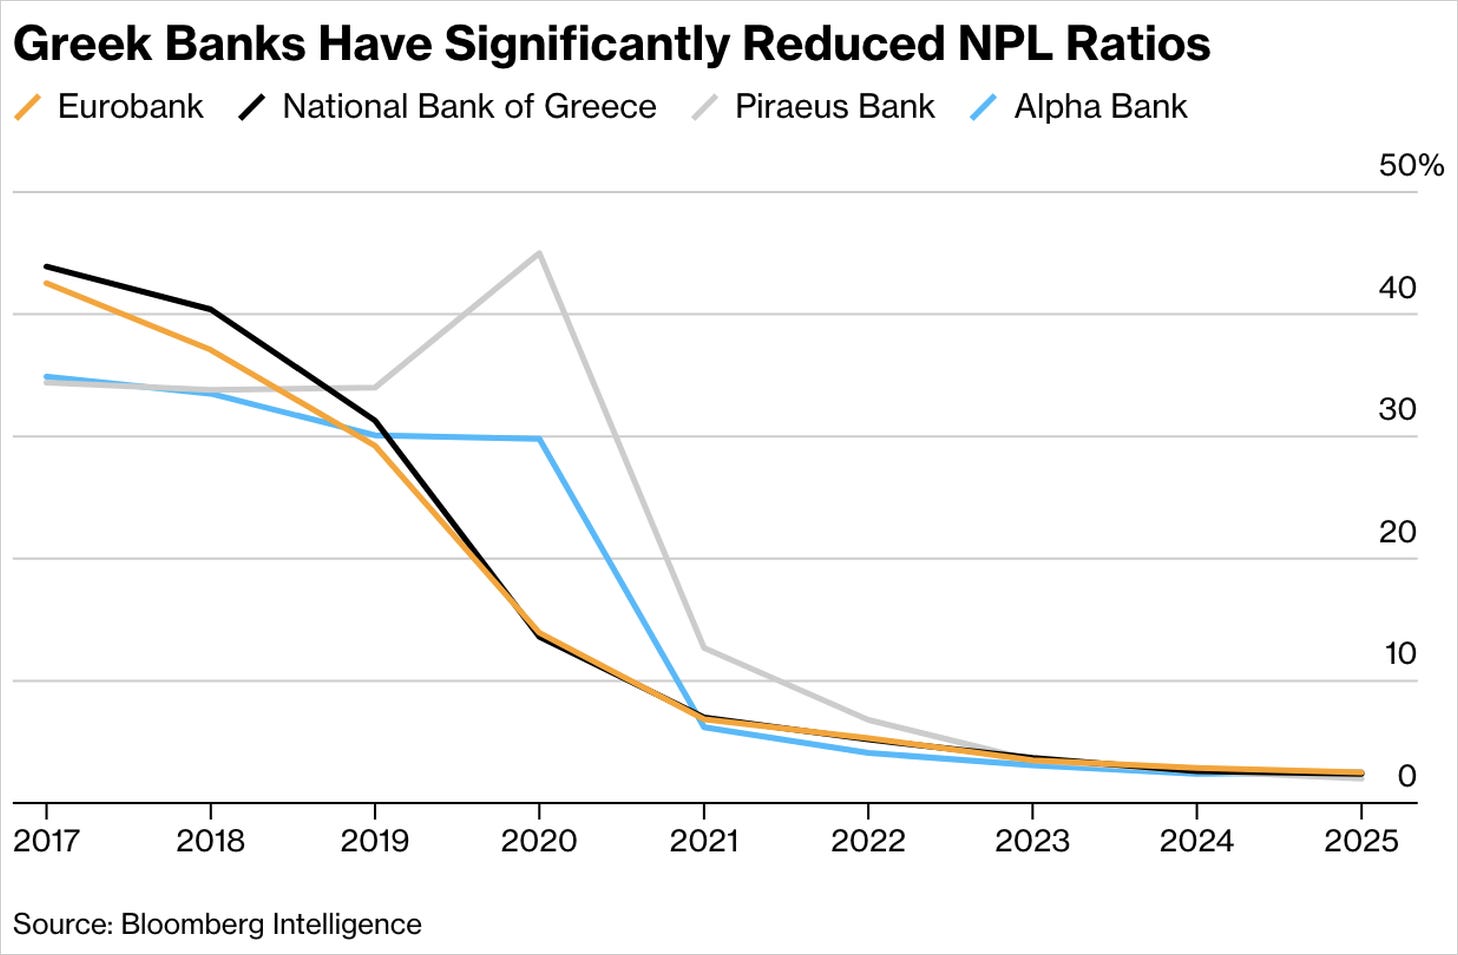
Greece’s financial-sector recovery has included a sharp decline in banks’ nonperforming loans. With STOXX restoring Greece to Developed Market status on September 21, National Bank of Greece, Eurobank, Piraeus Bank, and Alpha Bank are among nine Greek companies entering the STOXX Europe 600.
Europe
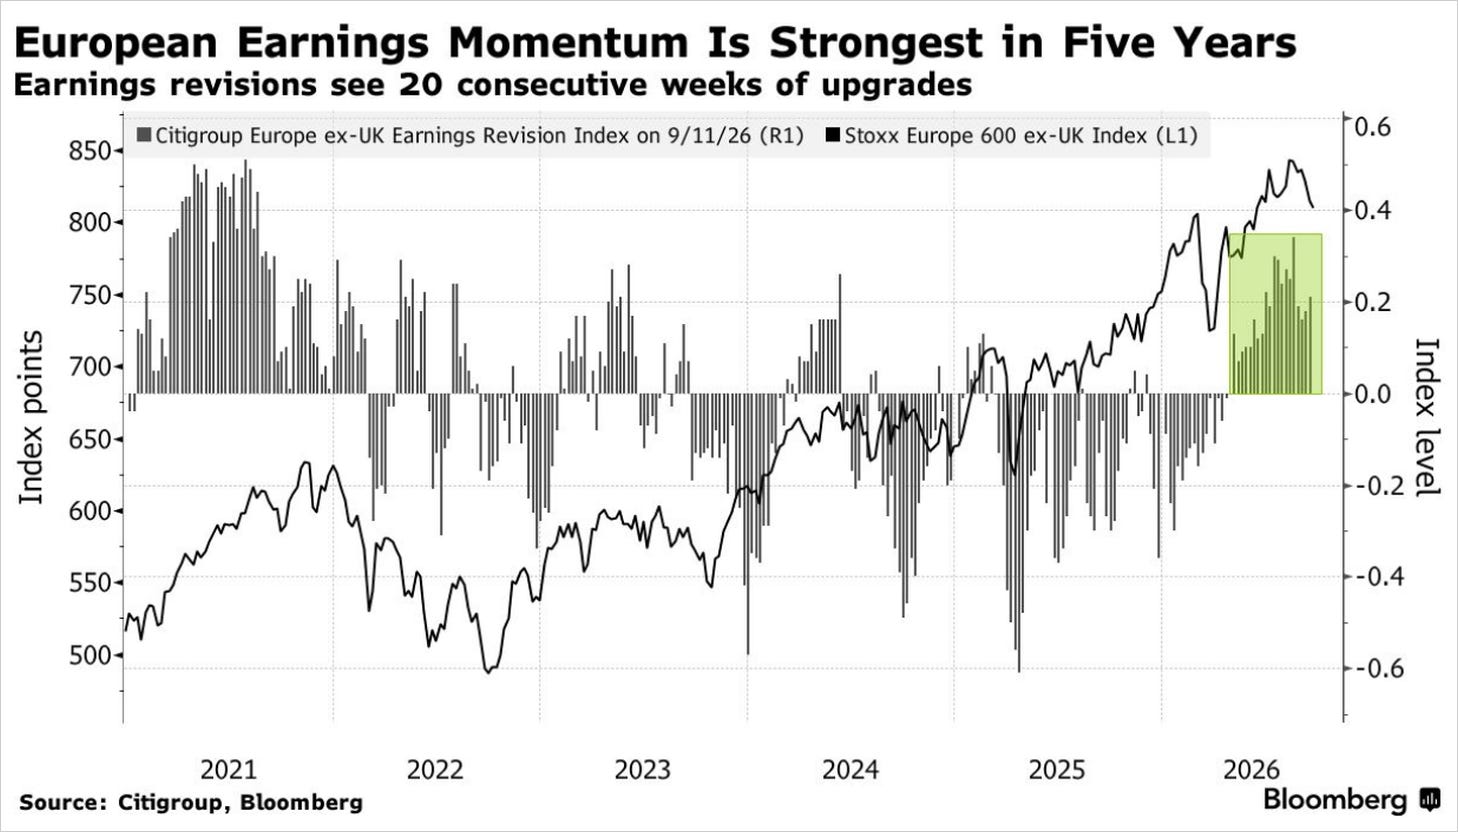
The European earnings-revision index has stayed positive for 20 straight weeks, its longest such streak in five years.
Japan
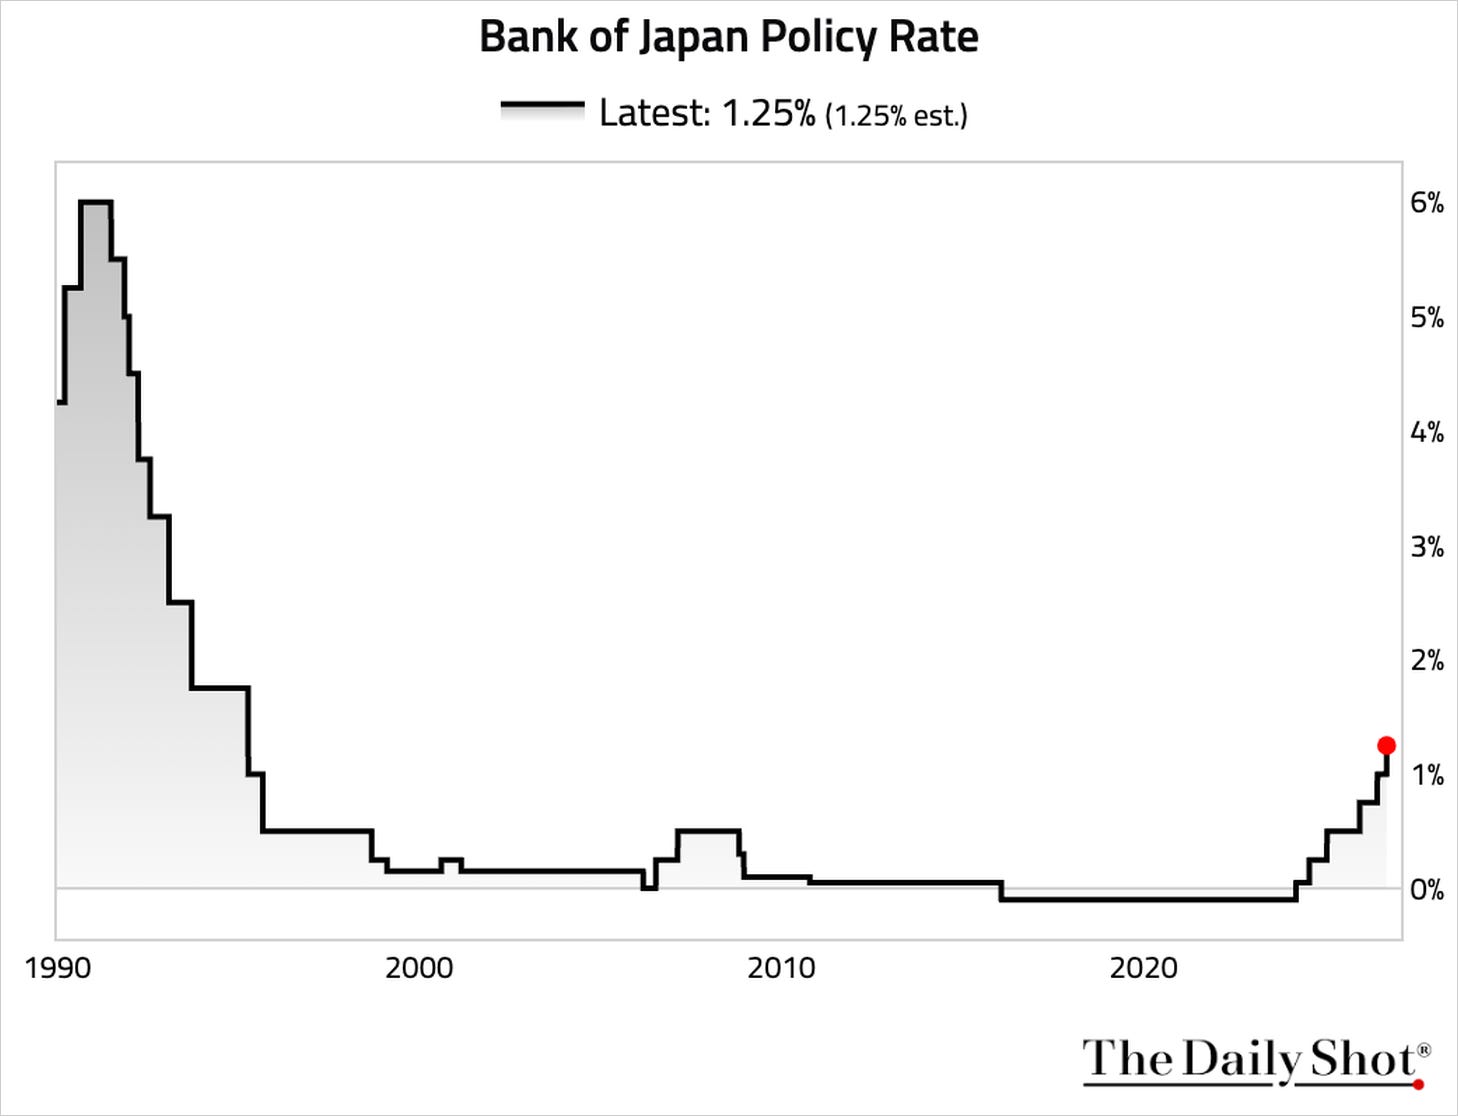
The Bank of Japan raised its policy rate by 25 basis points to 1.25%, its highest level since 1995, in a 7–2 vote as policymakers confronted persistent inflation pressures from wages, the weak yen, and elevated energy costs.
Equities
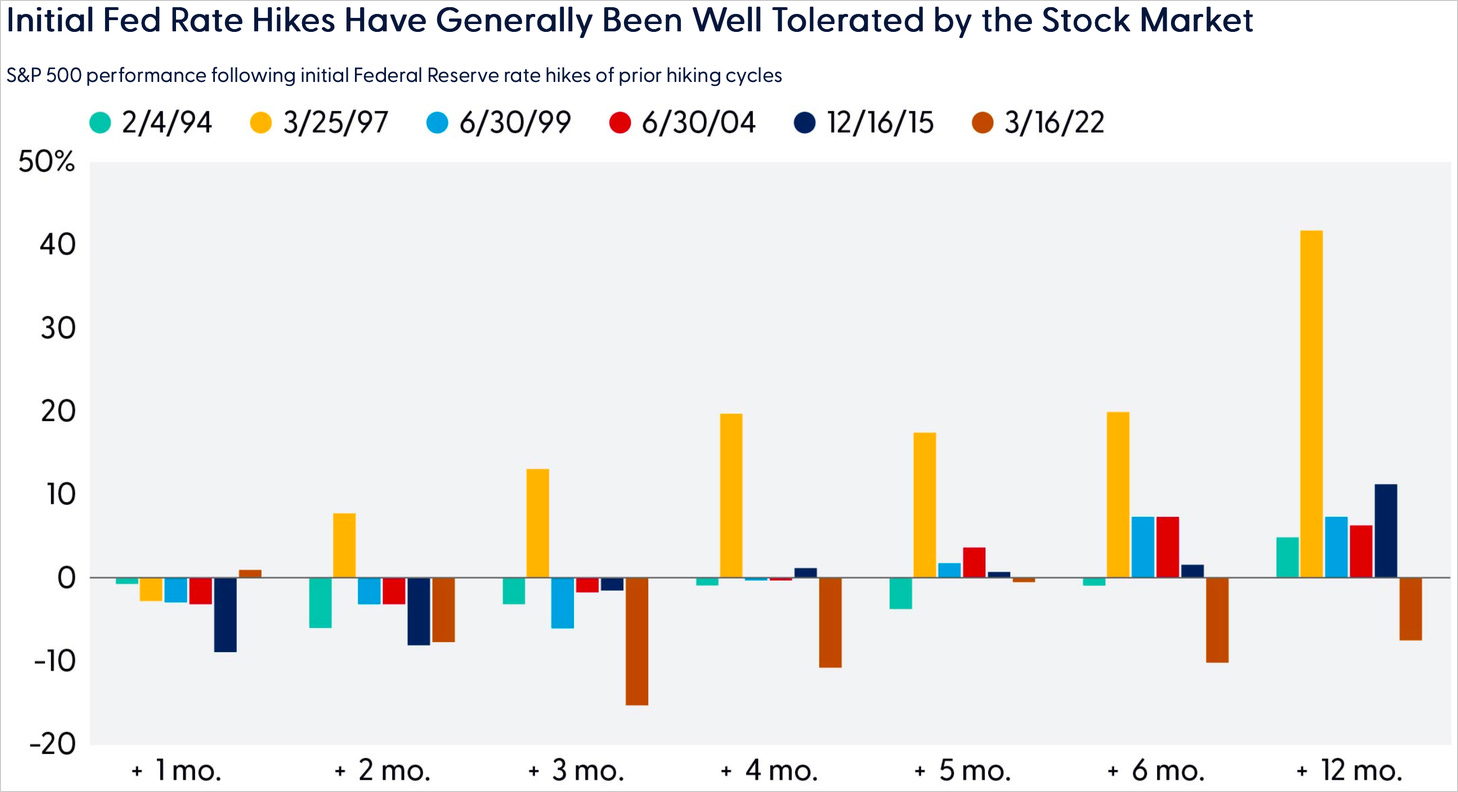
Historically, the S&P 500 has tended to struggle for several months after an initial Fed rate hike before recovering; across the six tightening cycles since 1994, the median 12-month return was 10.7%.
Rates
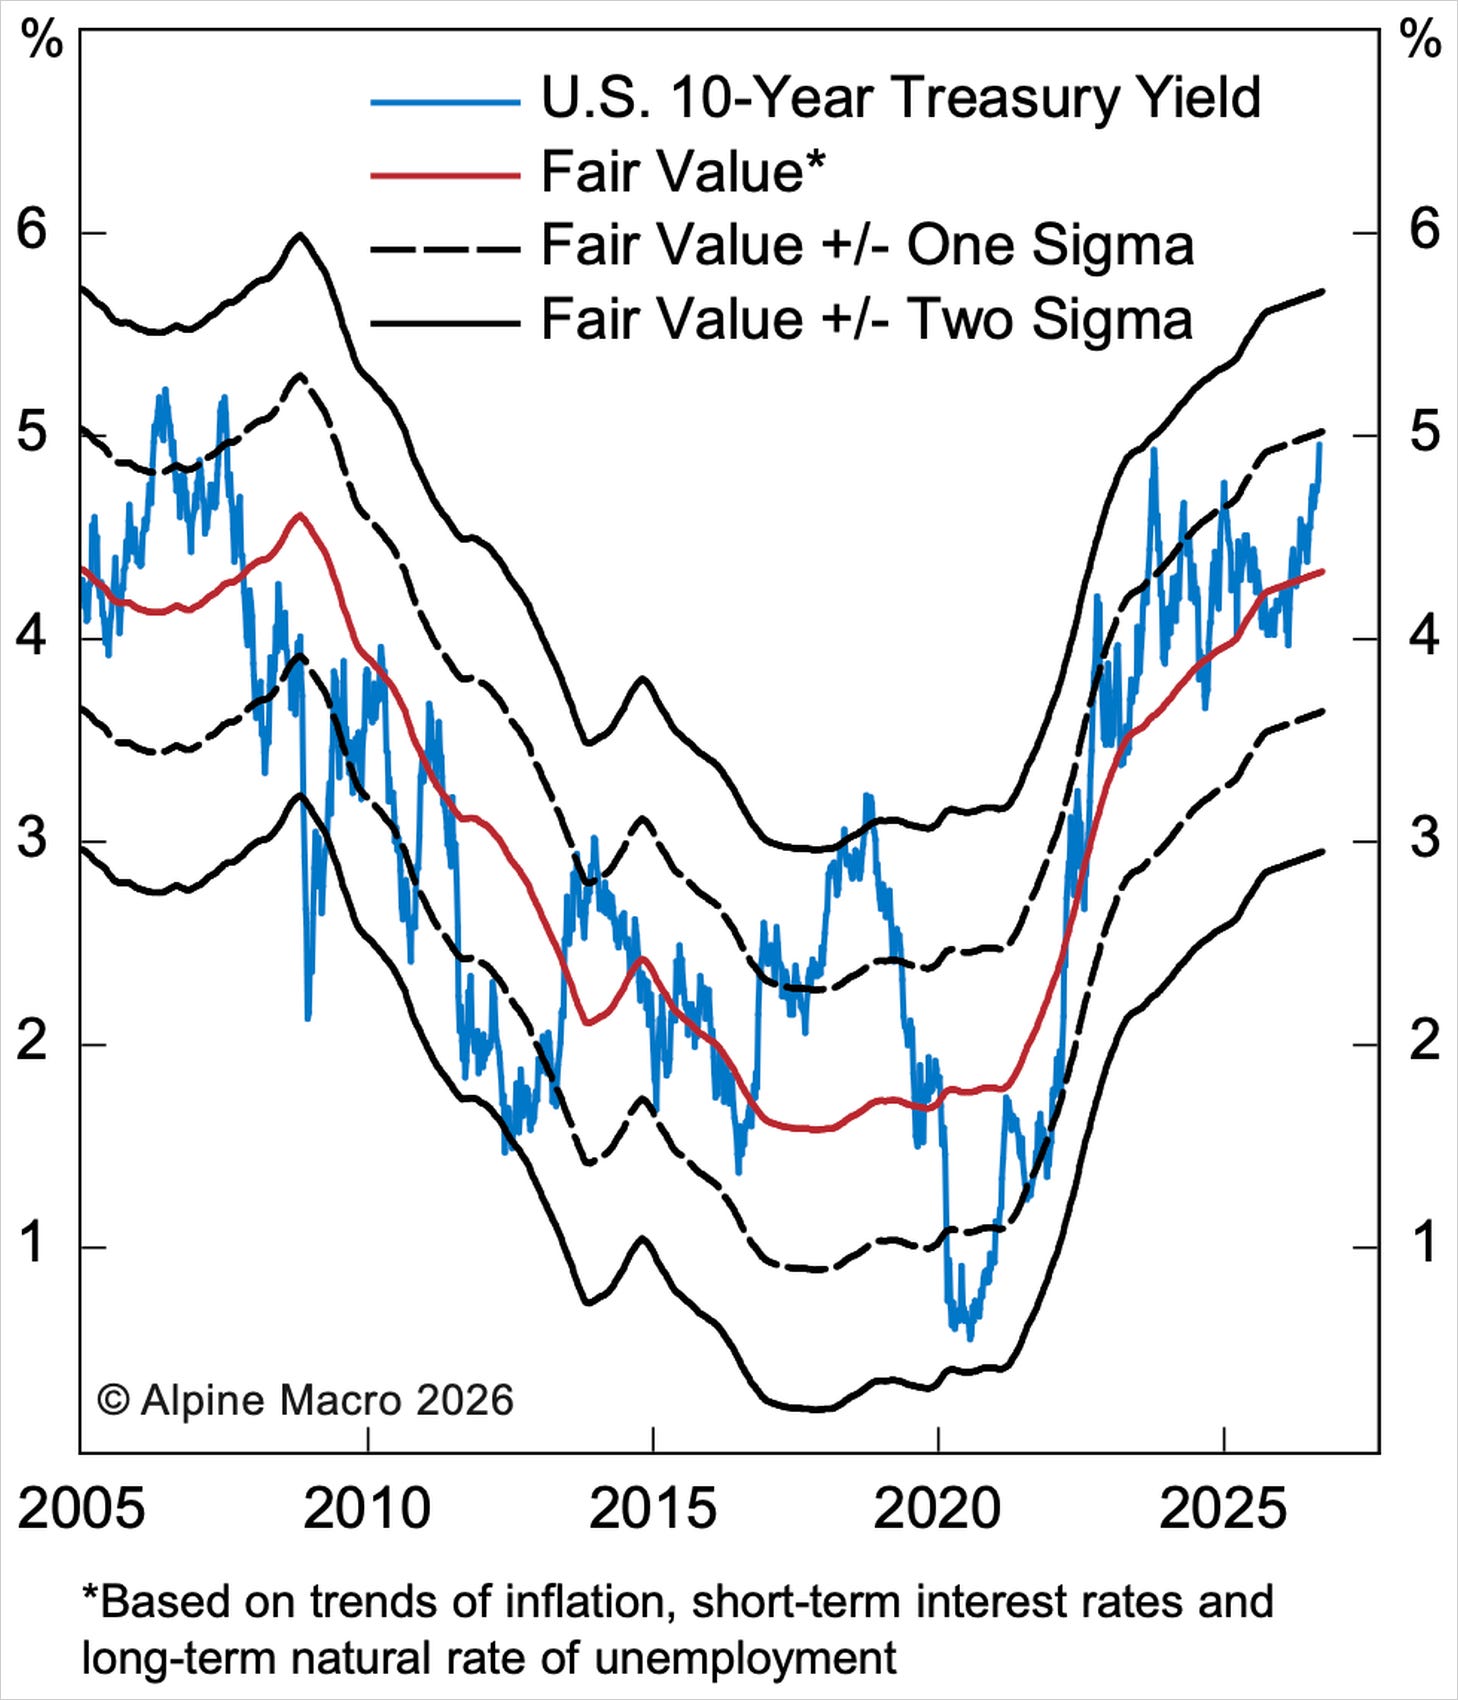
The 10-year Treasury yield is nearly one standard deviation above its fair value, according to Alpine Macro’s model.
Global Developments
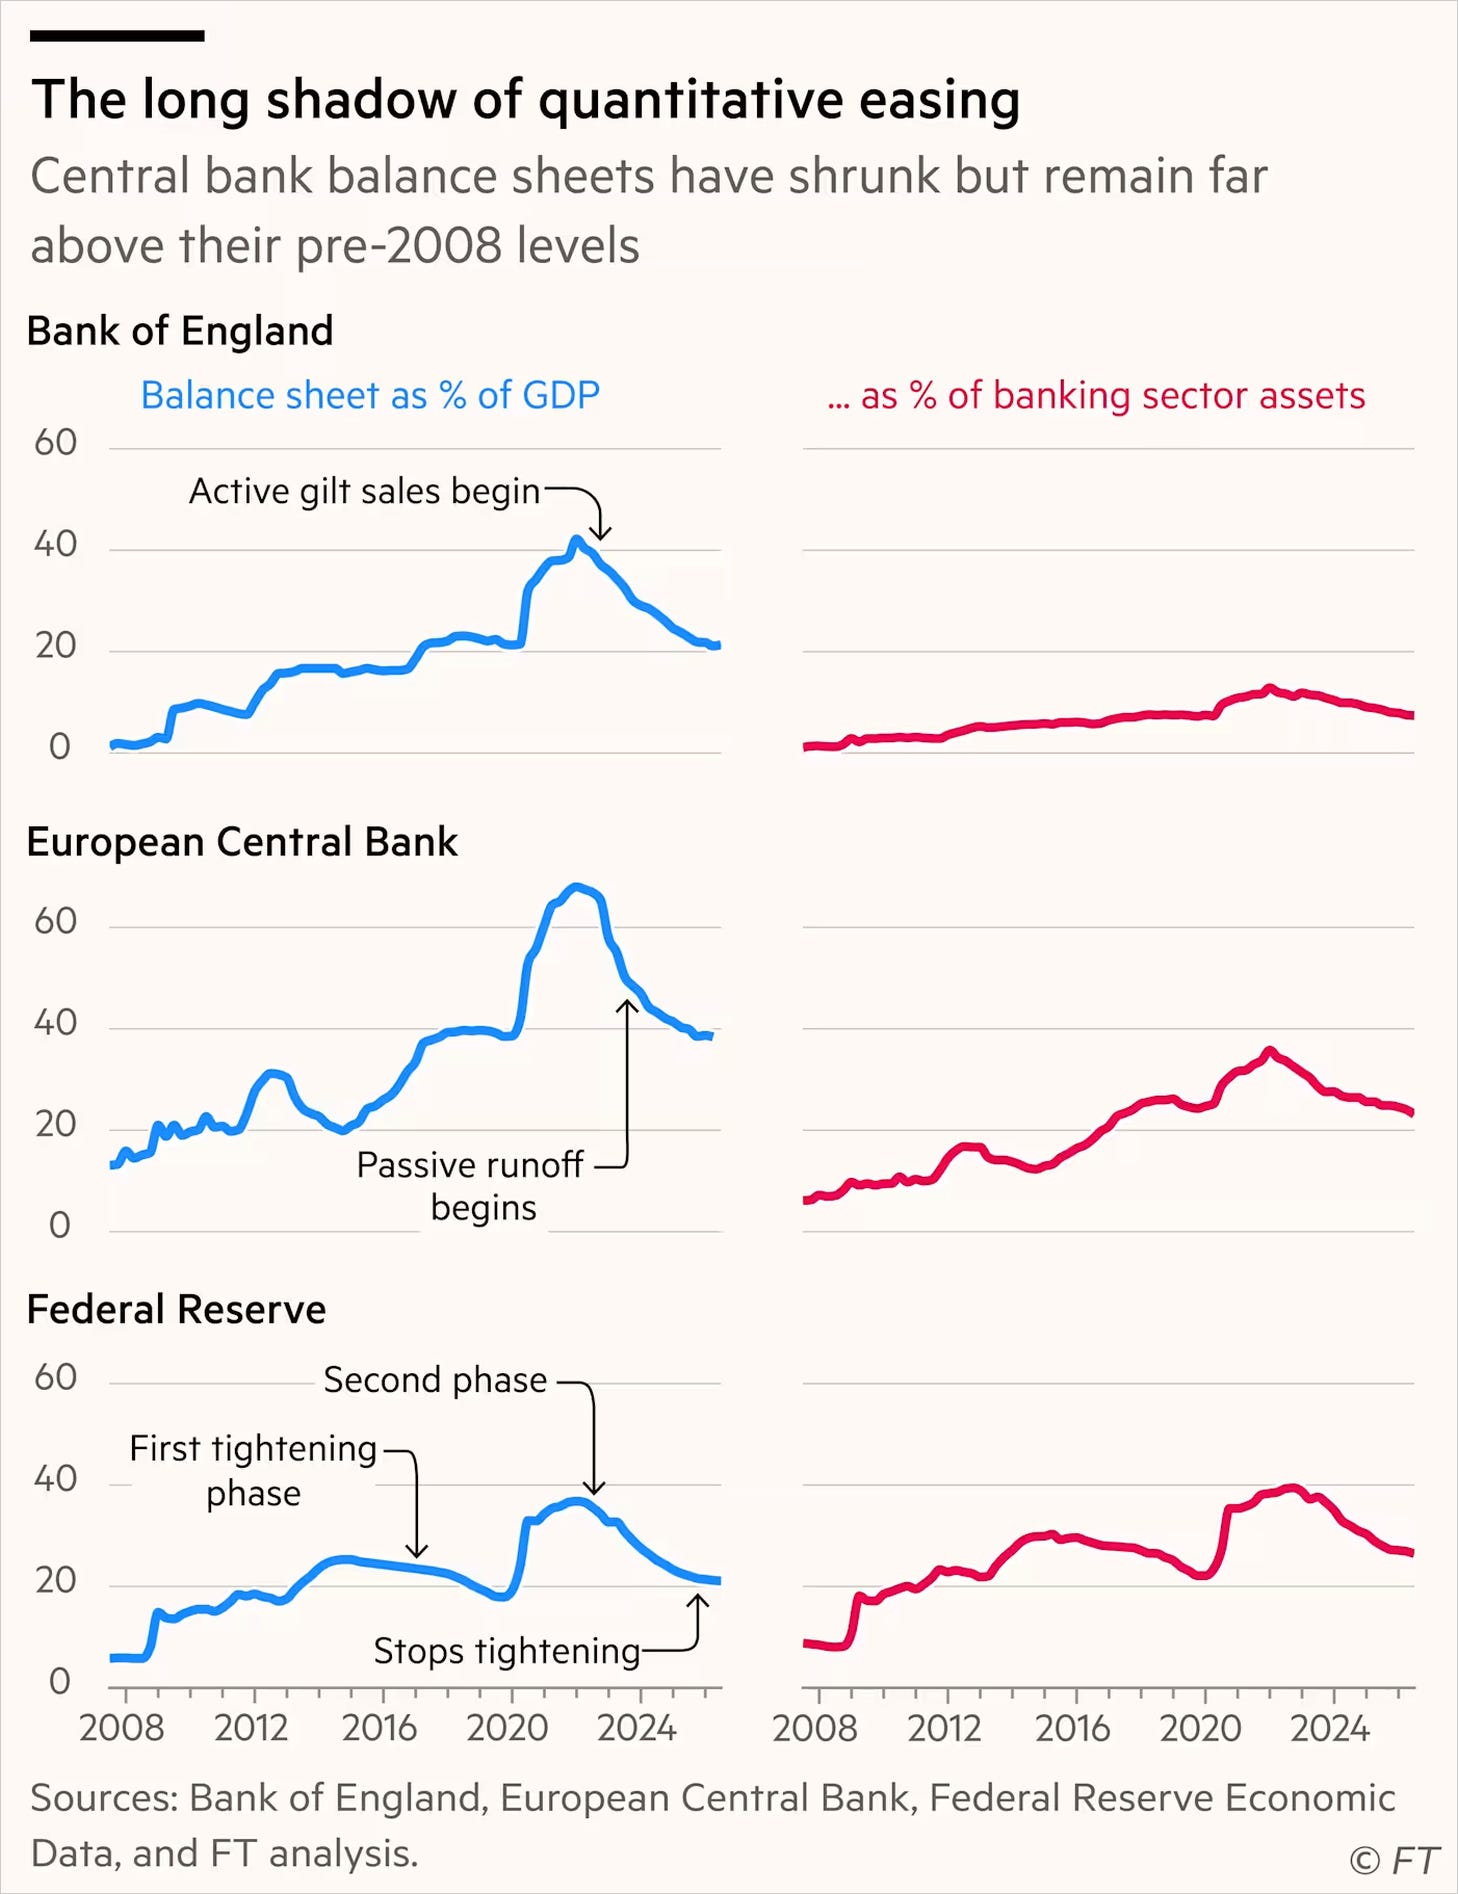
The balance sheets of the Fed, the ECB, and the Bank of England have been reduced to pre-pandemic levels relative to GDP. However, they remain well above pre-global-financial-crisis levels.