This is the Daily Shot Brief, an abridged version of The Daily Shot. If you would like to subscribe to the full-length Daily Shot (see example), please register here.
Rates
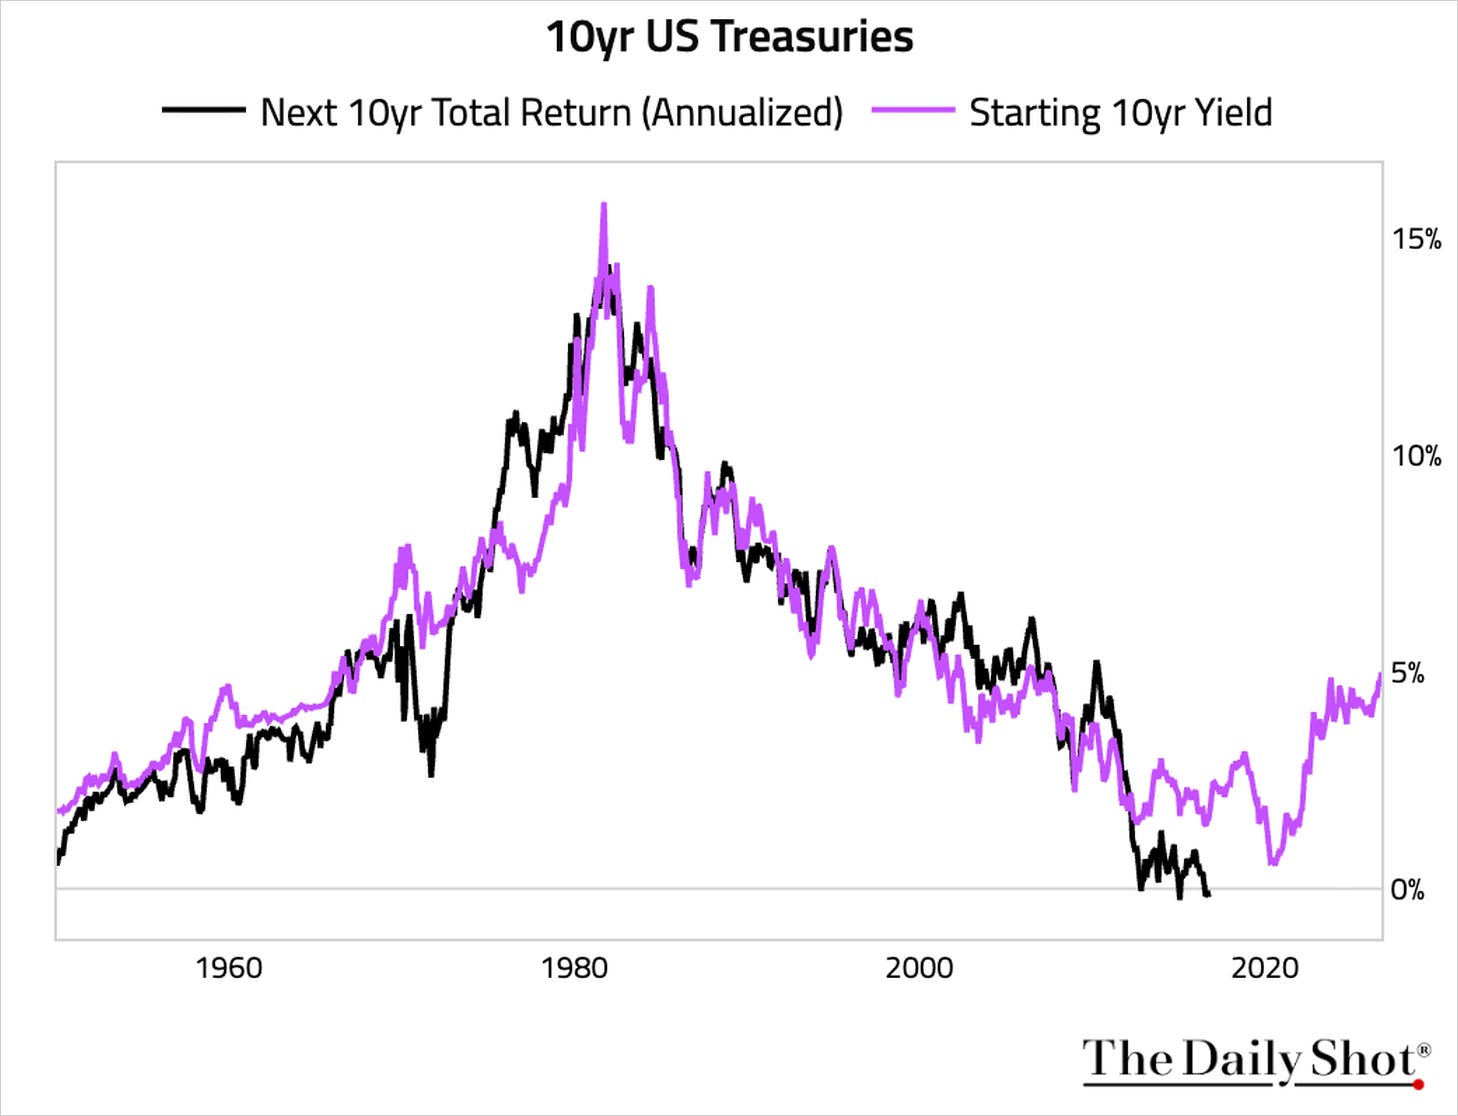
With yields moving higher, the longer-term return outlook has improved. This is because bond returns closely track their starting yields over the long run, whether an investor holds the bonds to maturity or rolls them periodically.
United States
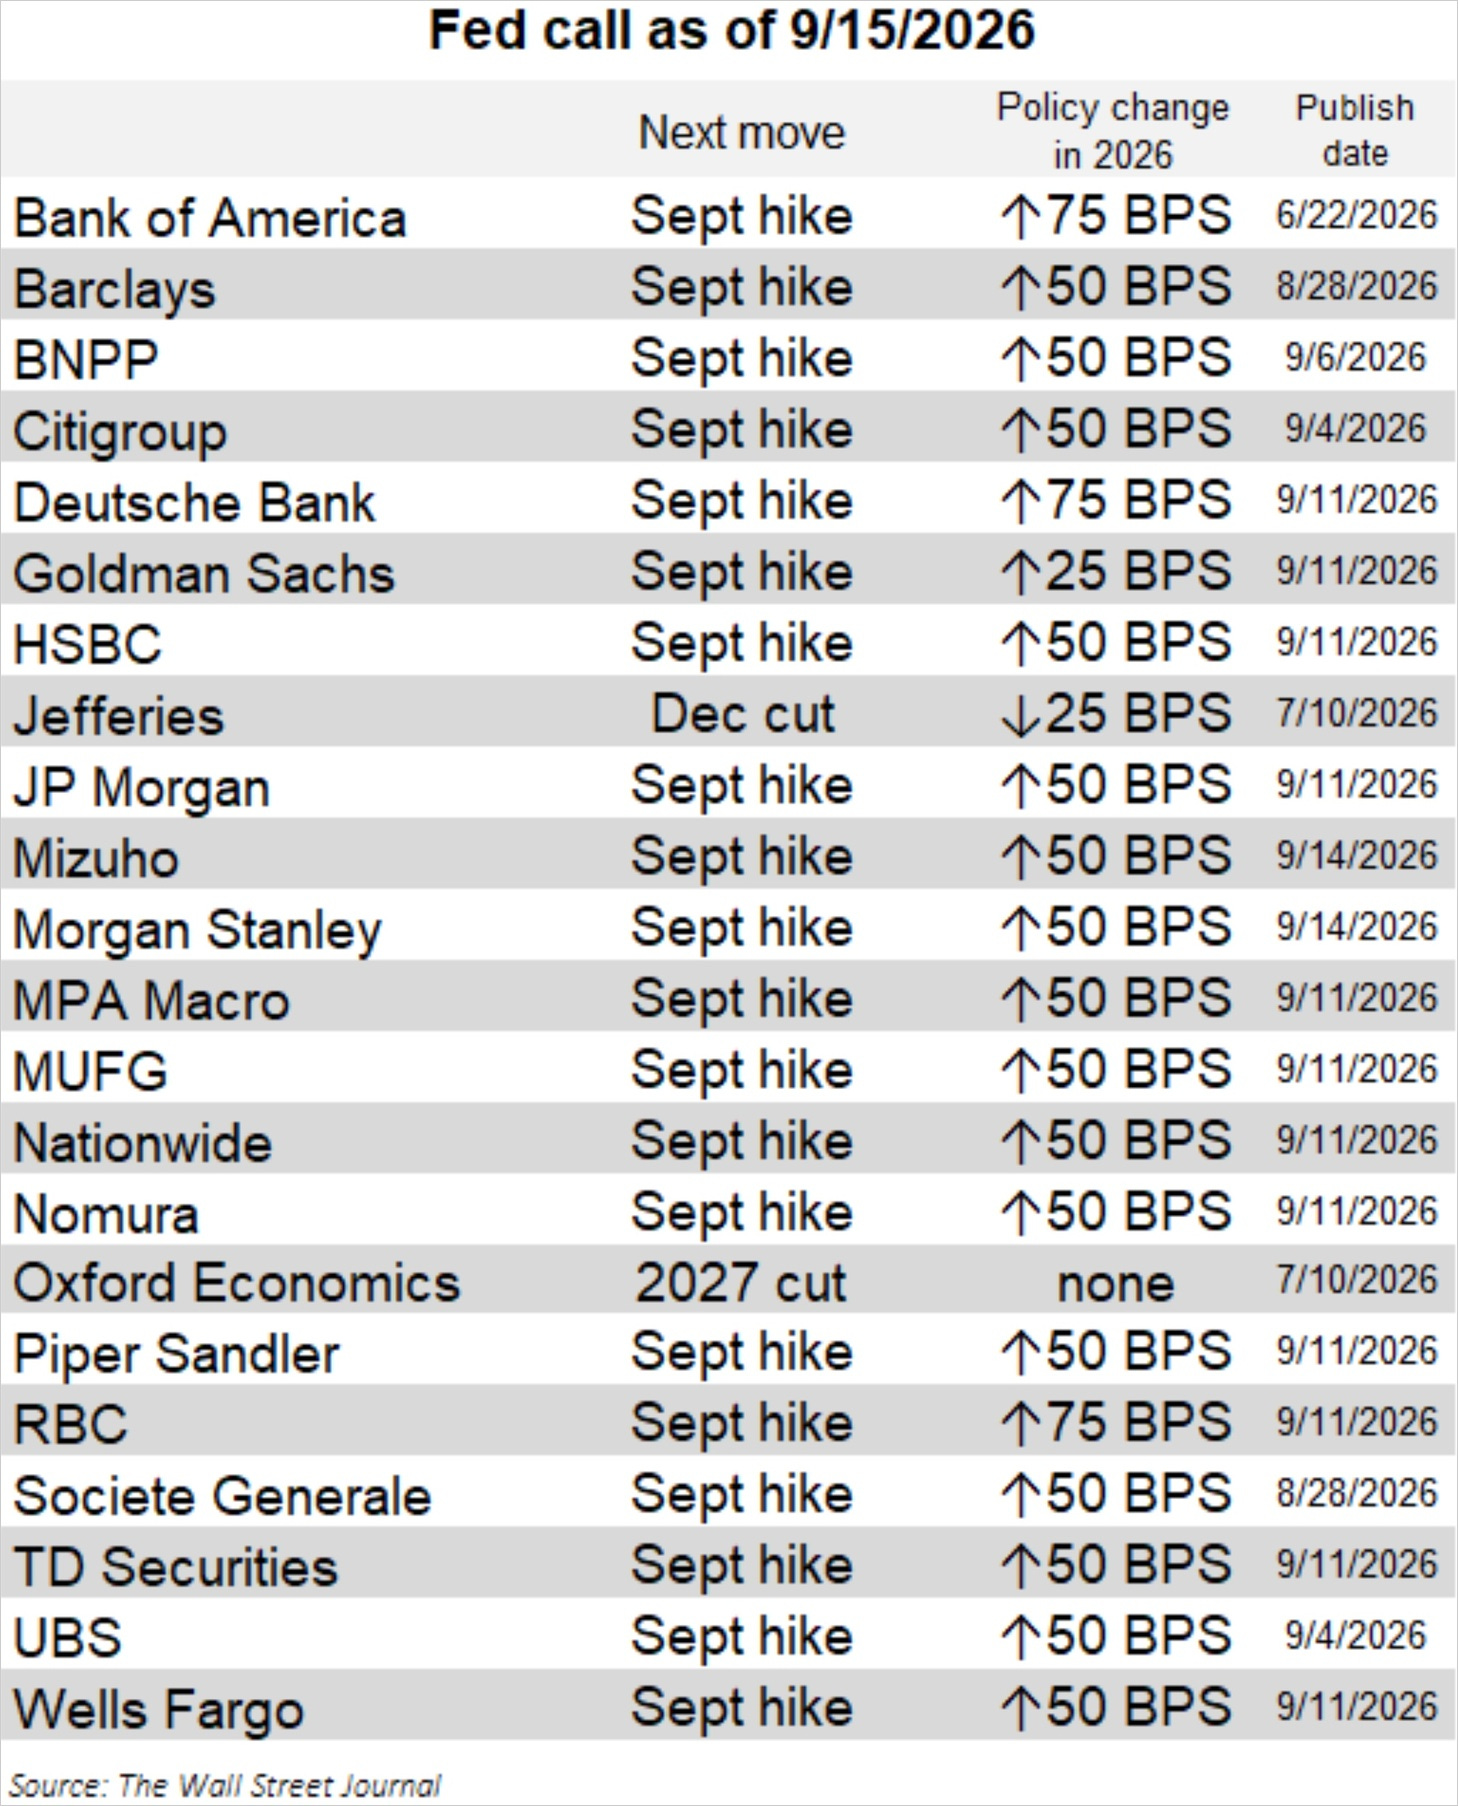
Here’s the latest look at economists’ Fed calls ahead of today’s FOMC decision. Not only are central bank watchers overwhelmingly expecting a rate hike today, most of them are also calling for at least a second hike before the end of the year.
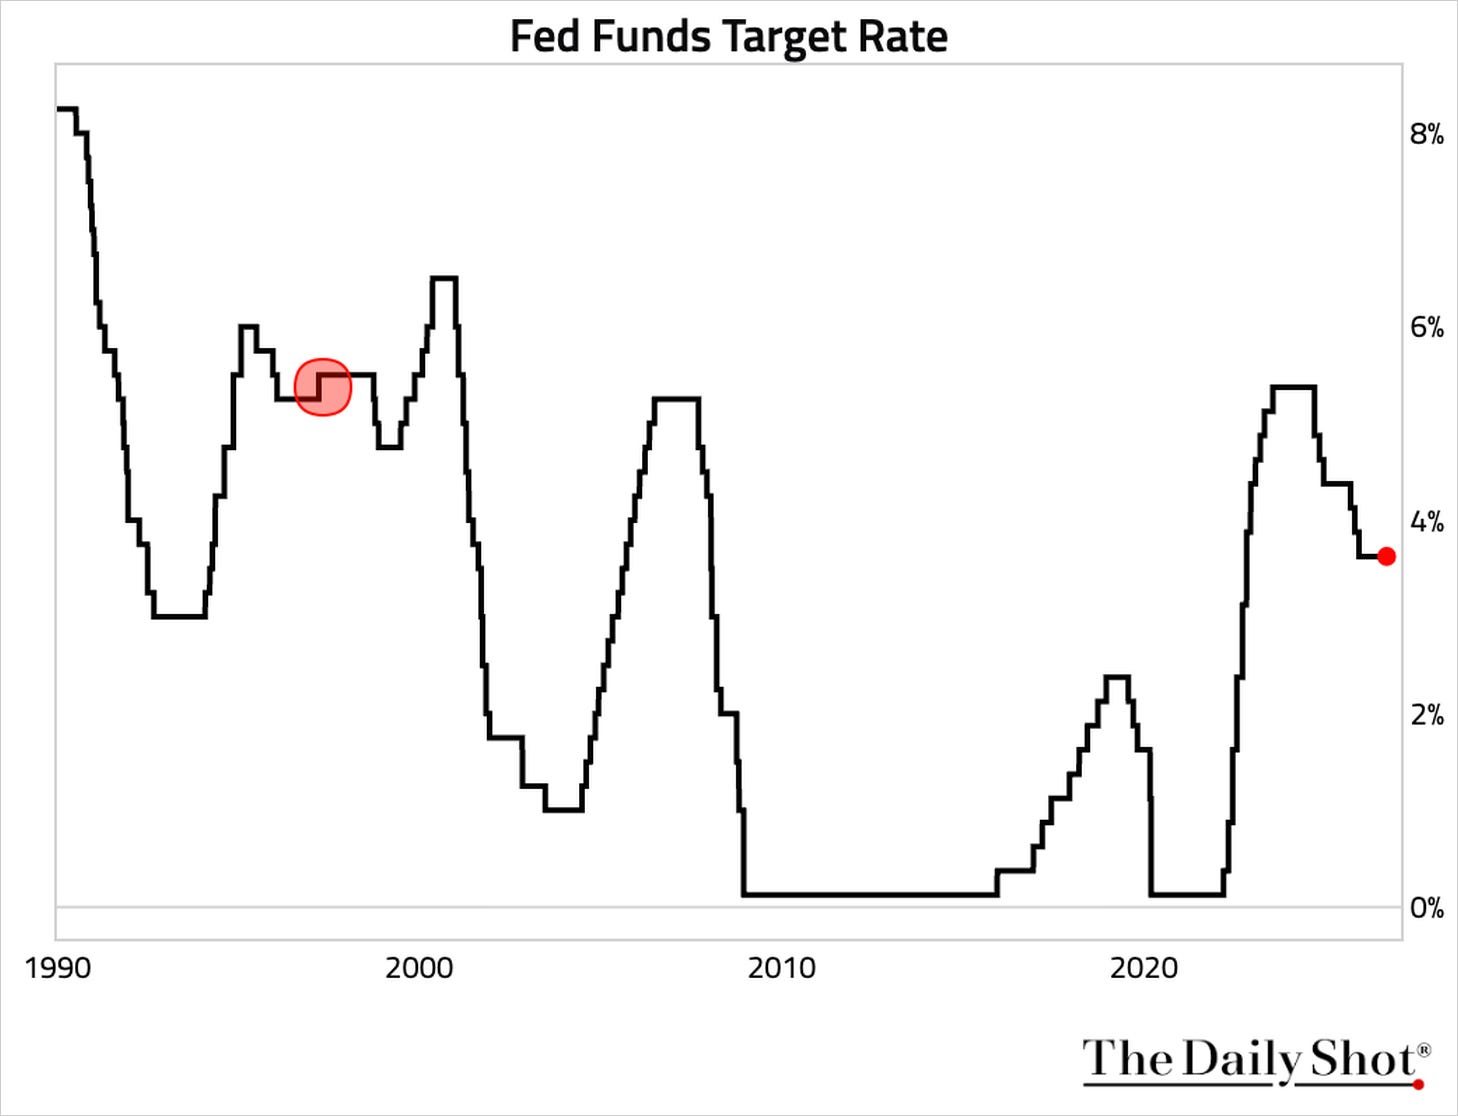
Single rate moves are rare—only 1997 stands out as a true one-and-done—supporting expectations that this week’s likely 25-basis-point hike will be followed by further tightening.
Canada
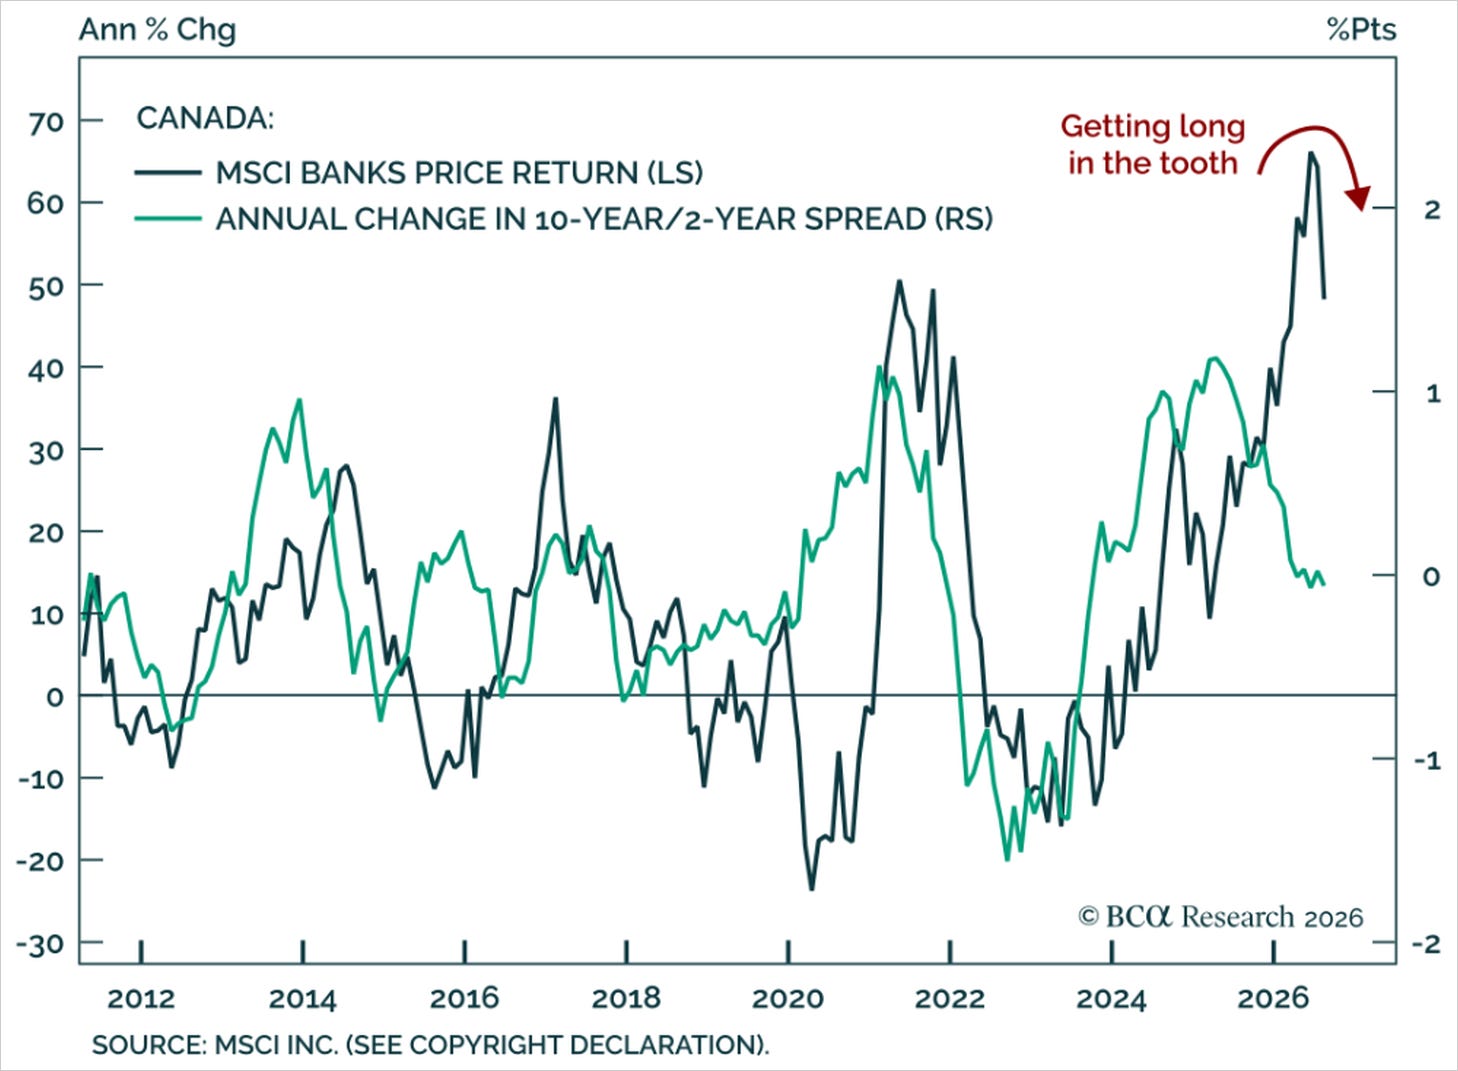
Canadian banks face growing downside risks from stretched valuations, housing weakness, and a fading yield-curve tailwind, according to BCA Research.
Europe
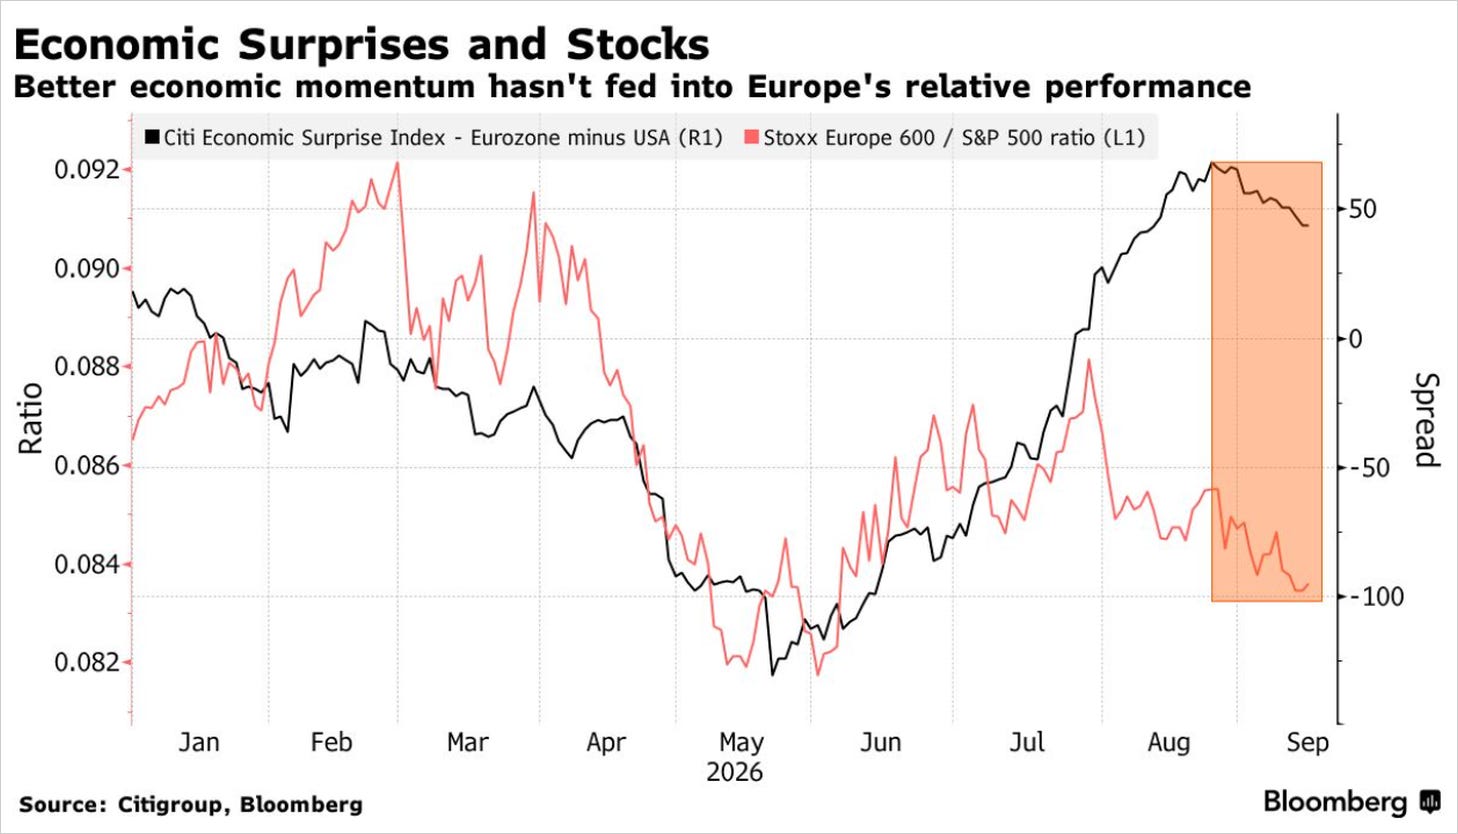
The Stoxx Europe 600 has underperformed the S&P 500, even as euro area economic surprises have outperformed.
China
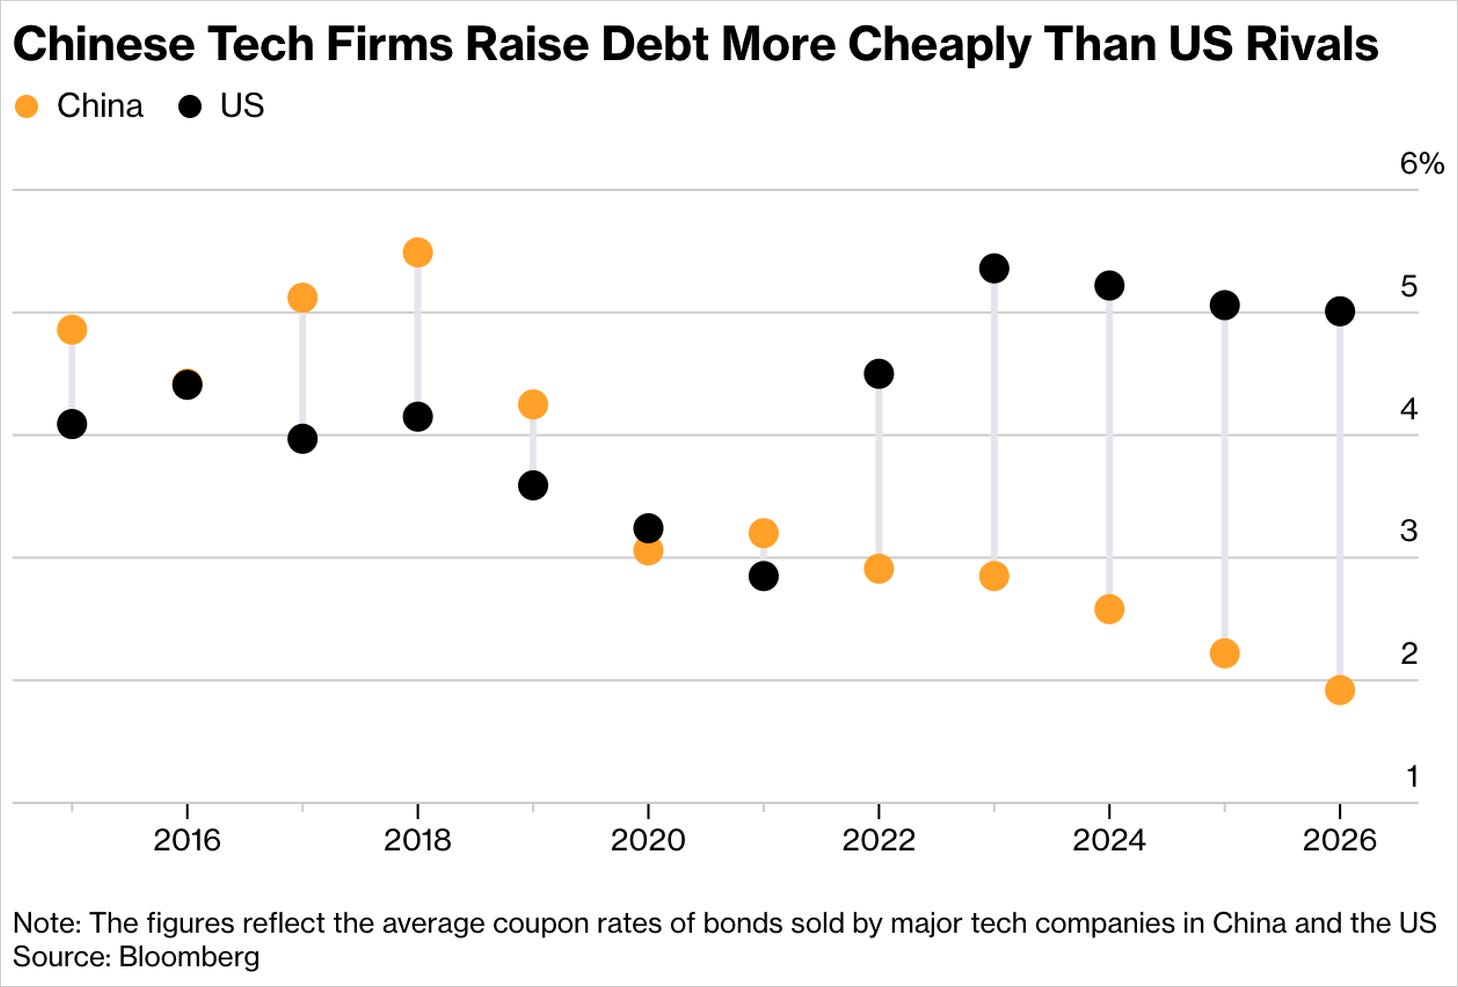
Bond coupon rates for major Chinese tech companies have fallen well below those of their American counterparts in recent years.
Equities
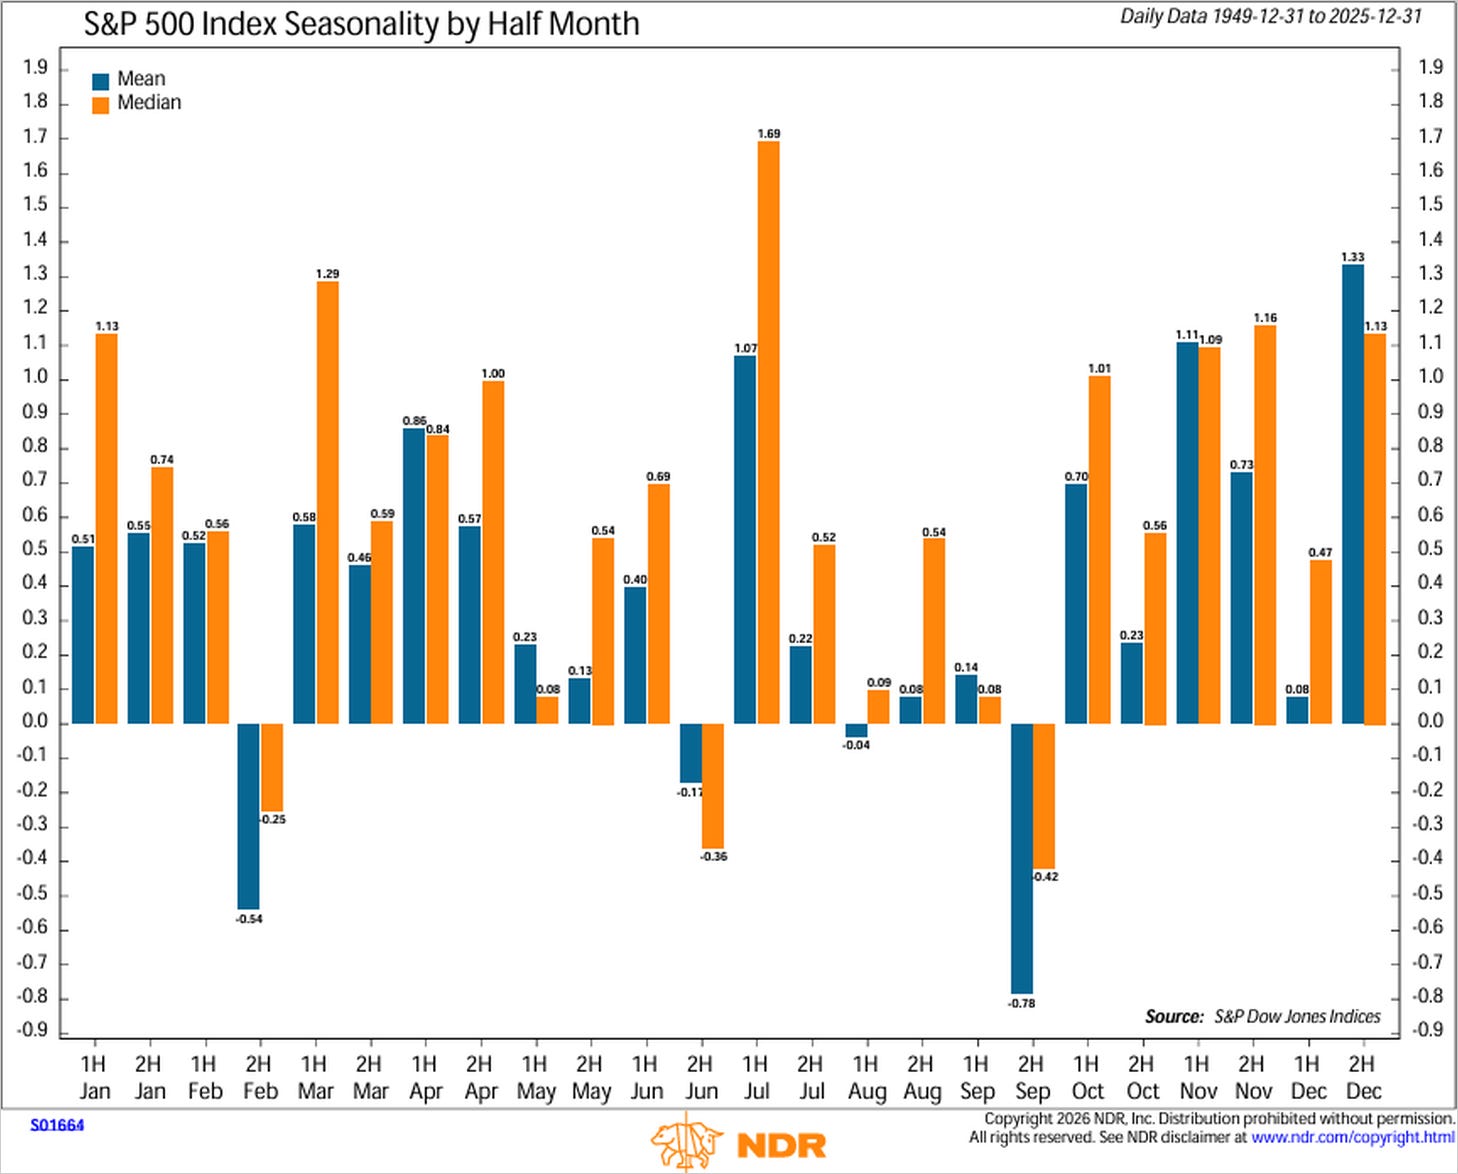
The second half of September has historically been the most bearish half-month of the year, based on both average and median returns.
Commodities
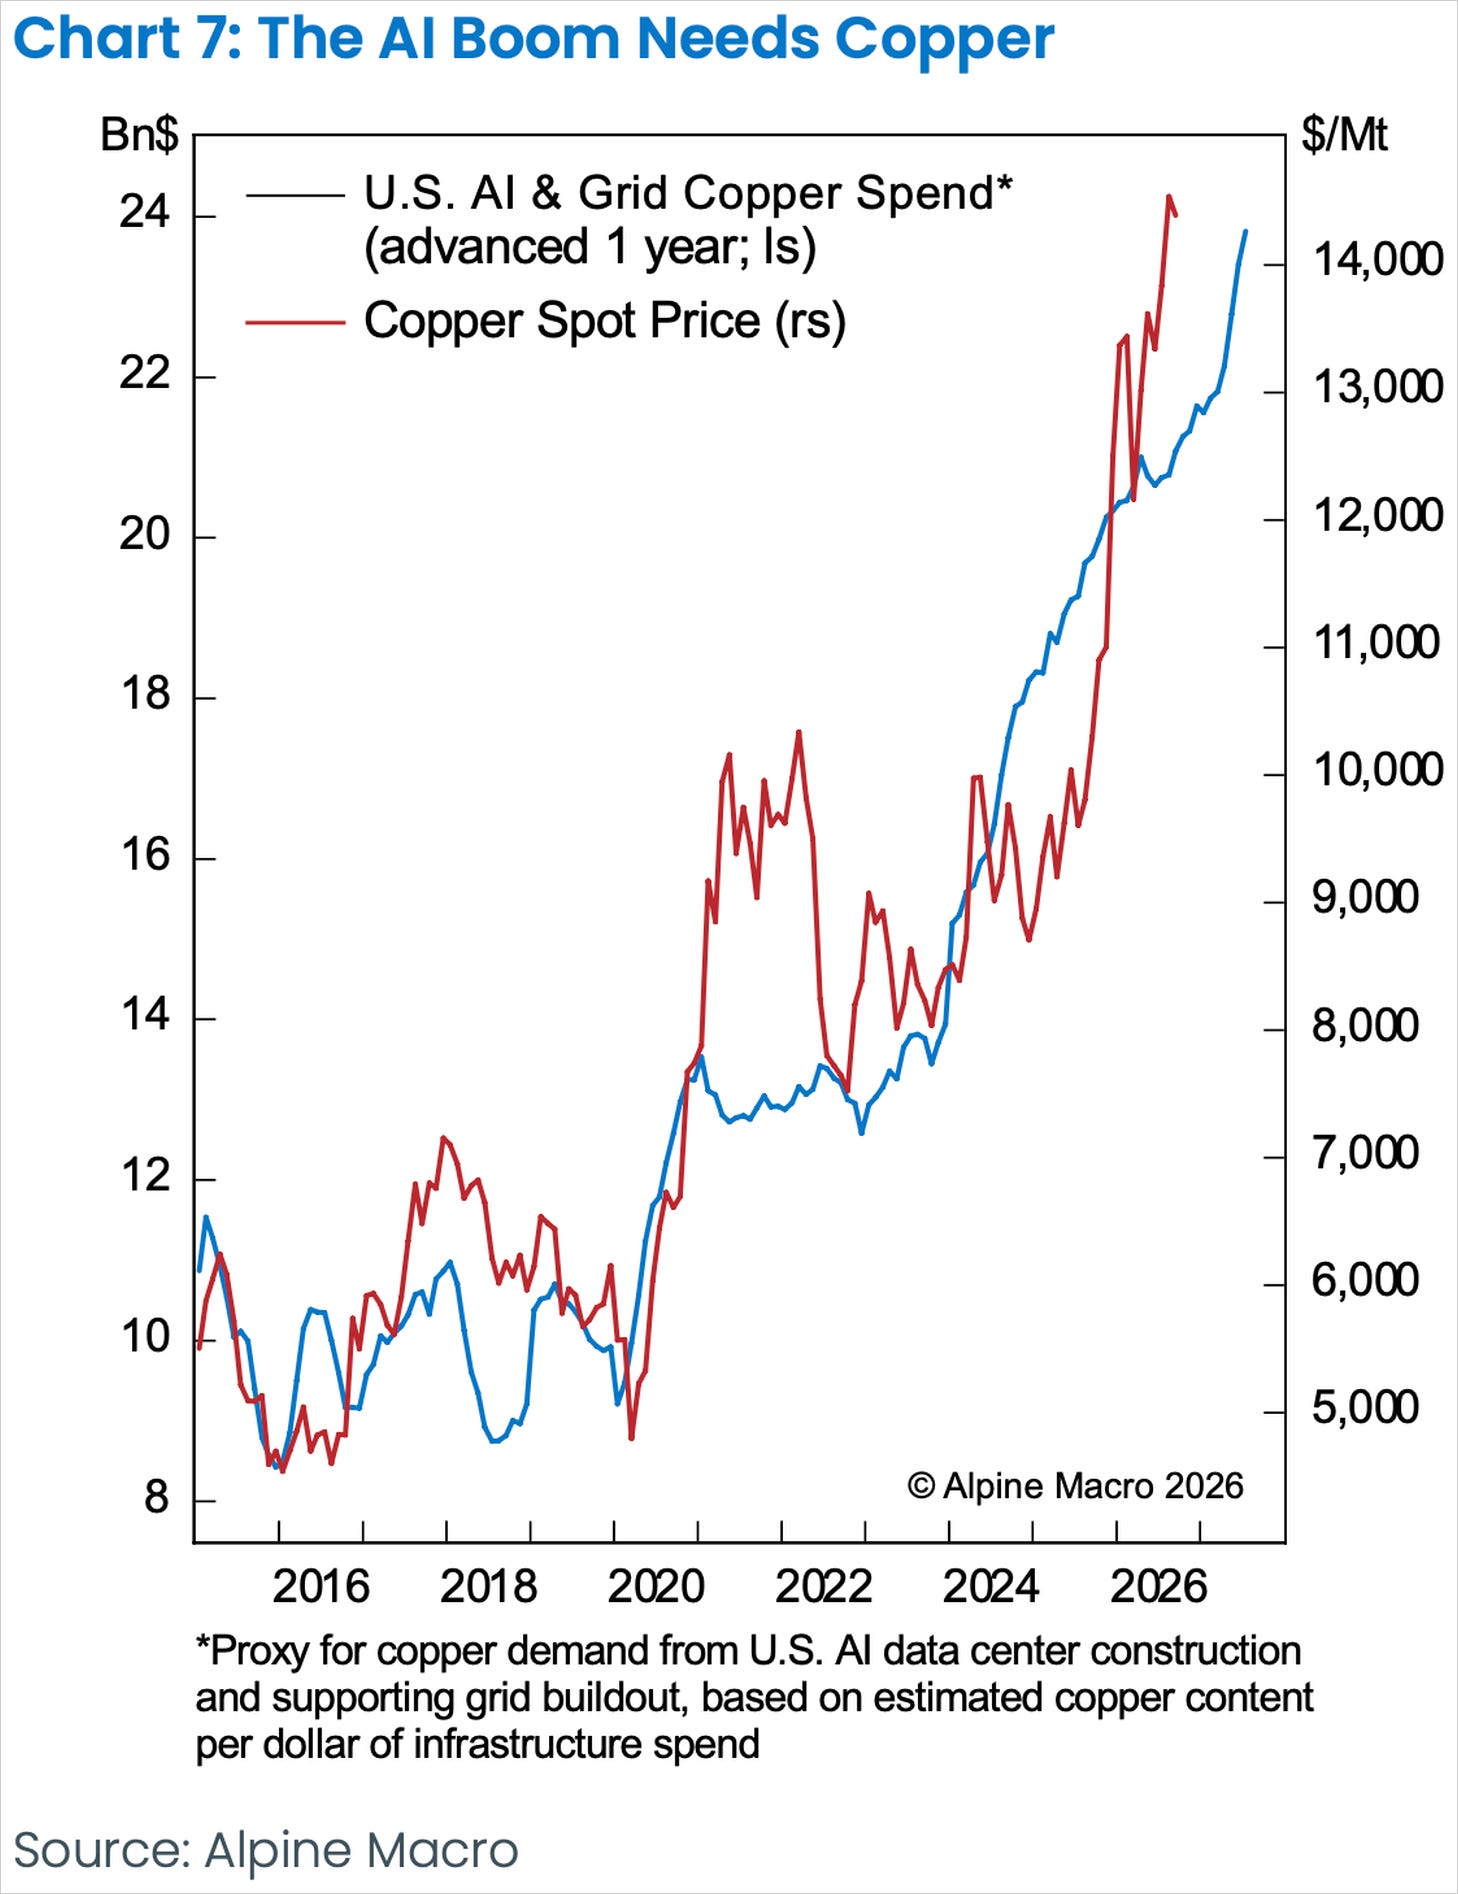
Data center and grid infrastructure involve substantial expenditures on copper, helping explain the rapid pace of copper price gains.
Energy
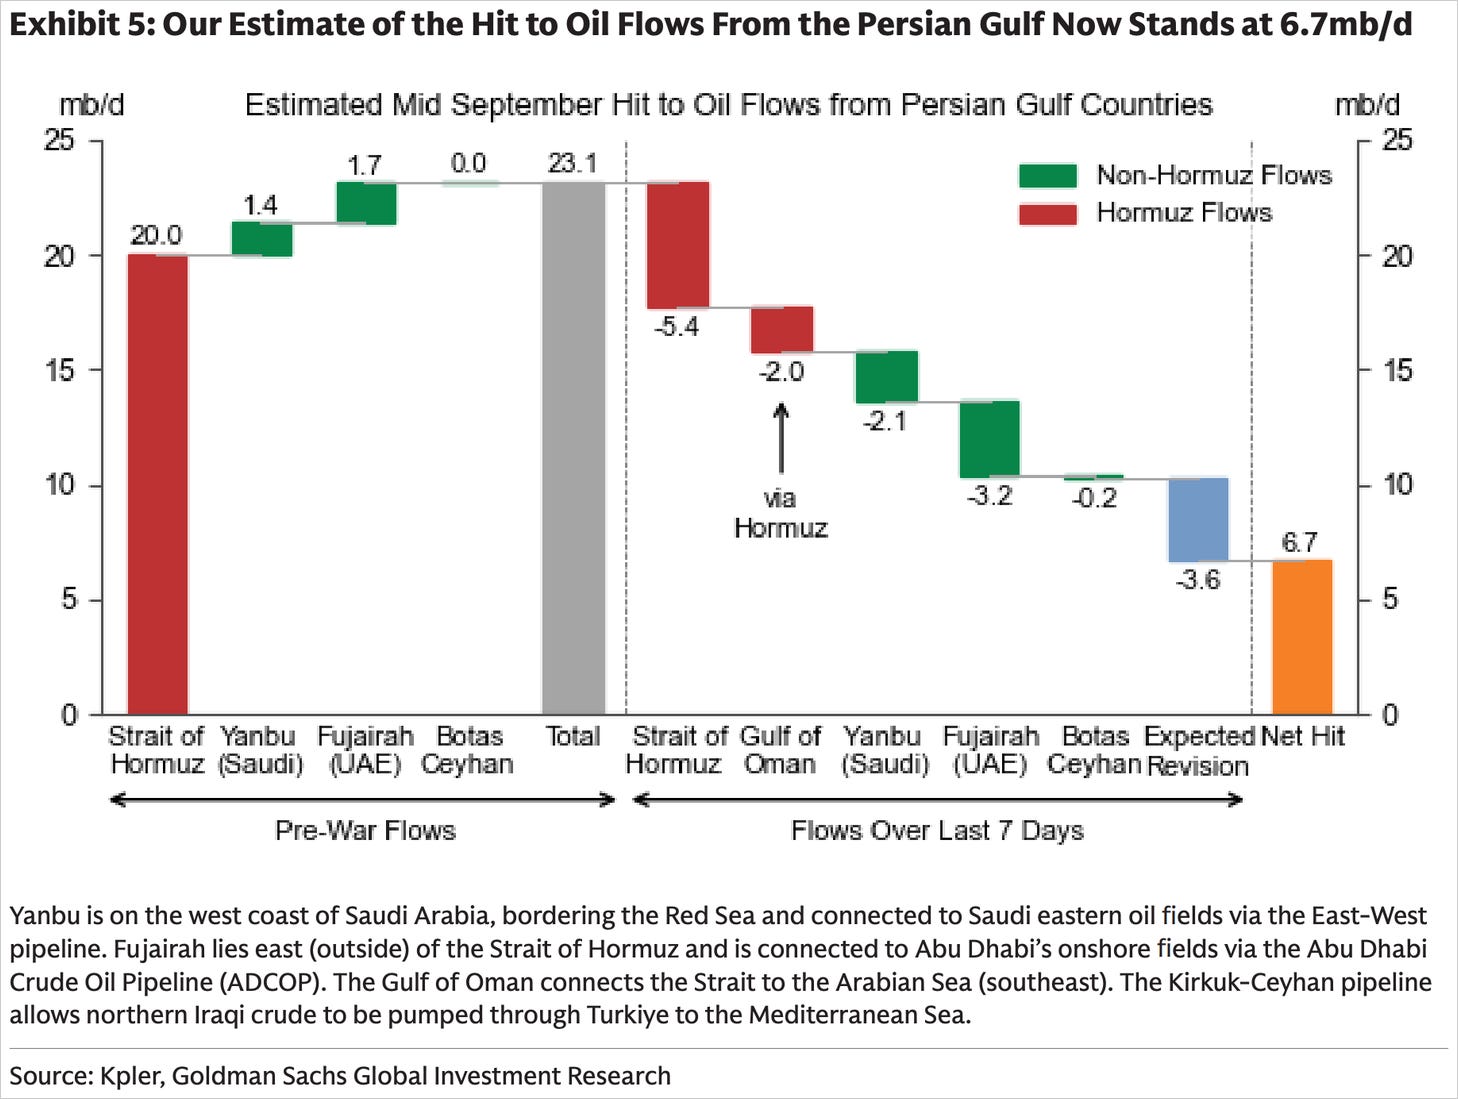
Goldman Sachs estimates that total Persian Gulf oil exports stand at approximately 16–17 million barrels per day, which is 6.7 million or 30% below pre-conflict levels.