This is the Daily Shot Brief, an abridged version of The Daily Shot. If you would like to subscribe to the full-length Daily Shot (see example), please register here.
Administrative Update
Final call to participate in The Daily Shot Pulse, our brief monthly survey of economic and market outlooks. Thanks to everyone who has already submitted responses; we will publish the results next week.
United States
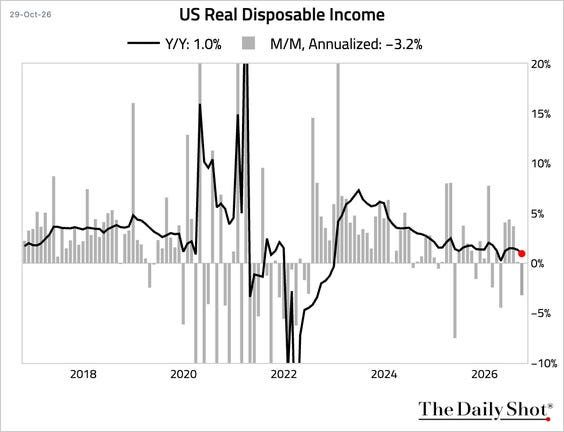
Real disposable income declined month over month.
Canada
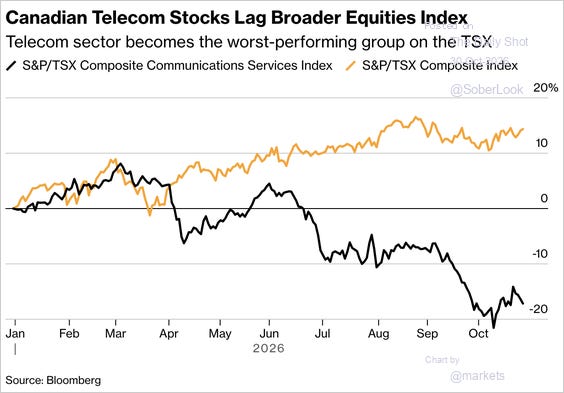
Canada’s communication services sector has substantially underperformed the broader TSX this year.
United Kingdom
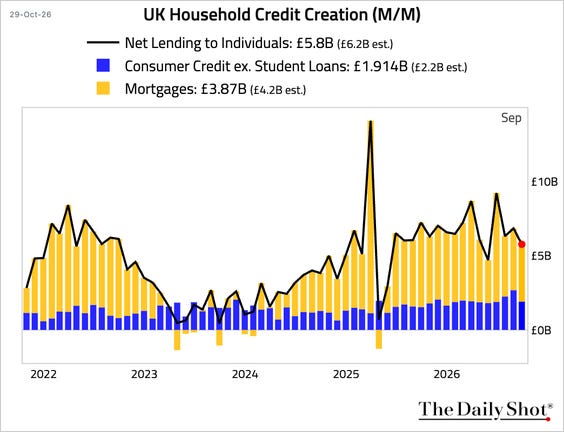
Household borrowing slowed in September, with both consumer credit and mortgage lending falling short of expectations.
Euro Area
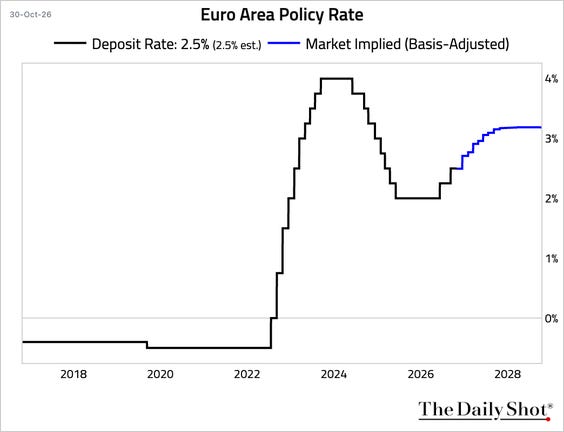
The ECB held interest rates steady, citing tighter financing conditions while warning that the energy shock poses upside risks to inflation and downside risks to growth.

Europe
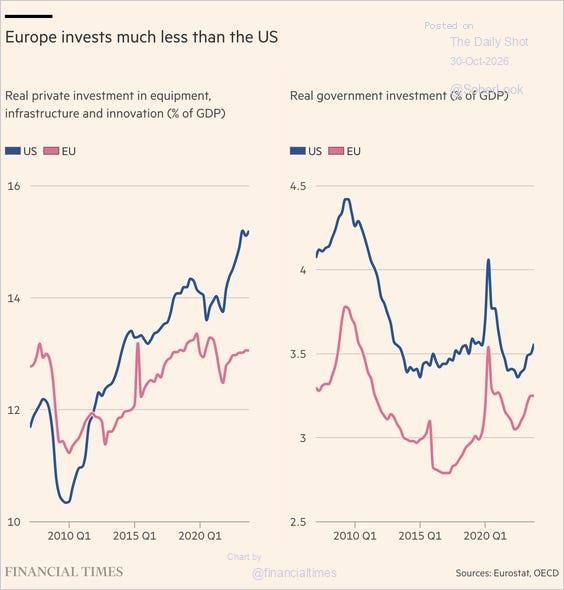
Private and public investment both account for smaller shares of GDP in the EU than in the US.
Japan
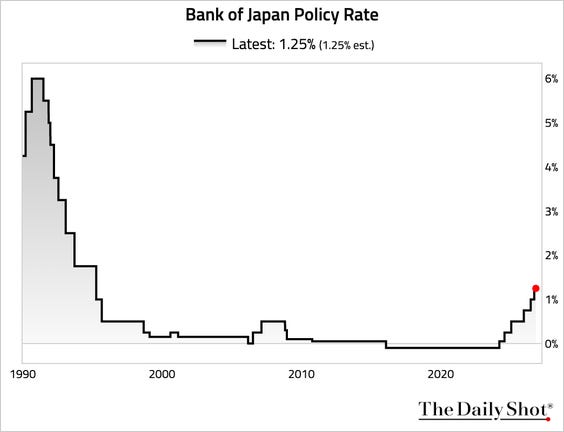
The Bank of Japan held its policy rate unchanged at 1.25% in an 8–1 vote, with board member Takata dissenting in favor of a 25-basis-point hike. The meeting struck a hawkish tone as policymakers stated that underlying inflation is now generally consistent with the 2% price stability target, shifted policy focus toward upside inflation risks, and nearly tripled ETF sales to about ¥860 billion a year starting in January.
Emerging Markets
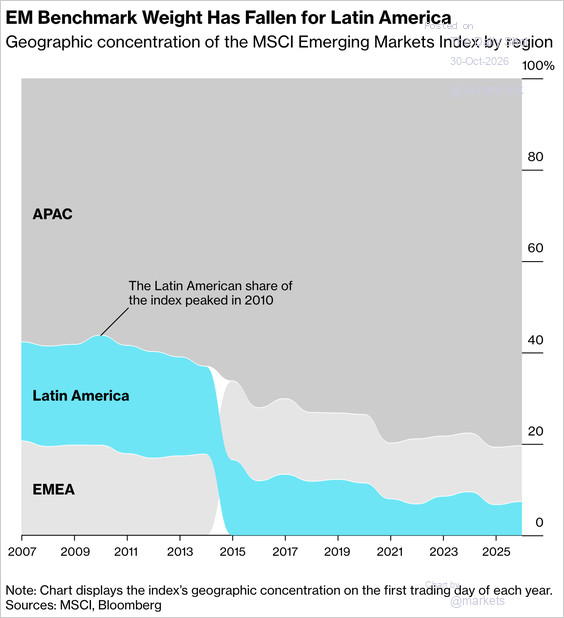
Latin America’s weight in the MSCI Emerging Markets Index has shrunk sharply since peaking in 2010.
Equities
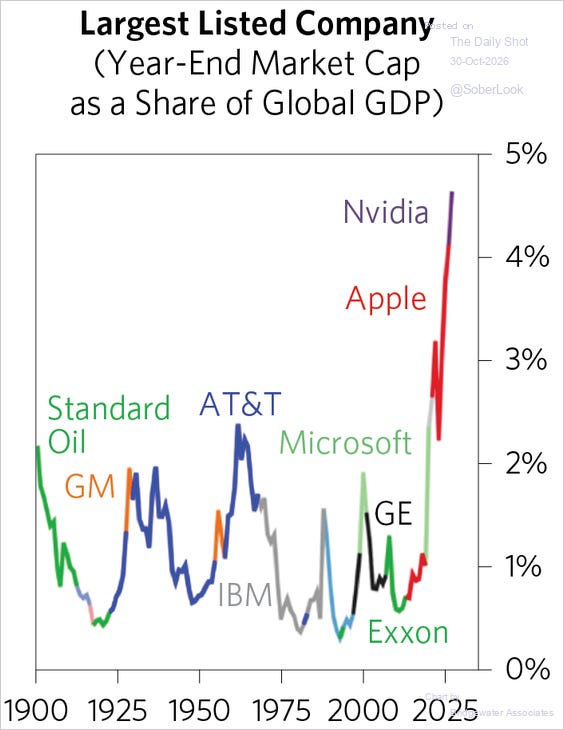
These are the largest listed companies in history.
Rates
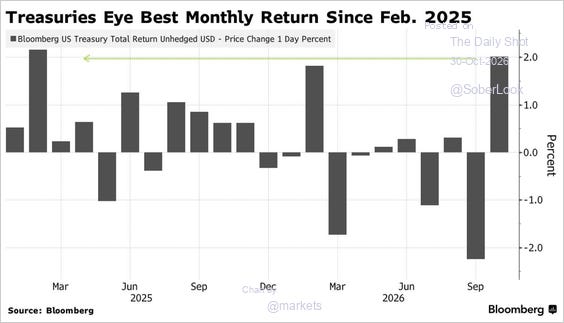
Treasuries rallied as the AI-driven technology selloff boosted demand for safe-haven assets, putting the benchmark index on track for its strongest monthly performance since February 2025.